FirstRand is hiring a Universal Advisor in Johannesburg for permanent branch banking work
What branch banking actually looks like inside a major South African lender, how compliance shapes the daily floor, and where this job leads.
The sector this sits in
Retail banking in South Africa is undergoing a steady transformation. Over the past decade, the Big Four and newer digital-first entrants have spent billions moving basic transactional activity out of physical brick-and-mortar buildings and onto mobile apps. You no longer need to walk into a banking hall to get a statement, transfer cash, or open a low-tier savings account. Yet, physical branches have not disappeared. Instead, their entire reason for existing has shifted.
Branch networks are now conversion hubs and problem-solving centres. When people walk through the door of a branch in Johannesburg, they generally fall into two categories: customers dealing with complex disputes that a chatbot could not resolve, or individuals looking for credit, investment products, or business services that require human trust and regulatory verification. Because South African banking operates under intense regulatory oversight, specifically the Financial Advisory and Intermediary Services (FAIS) Act and the Financial Intelligence Centre Act (FICA), every conversation across a desk carries legal weight. Lenders face massive penalties if staff push products to people who cannot afford them, or if staff fail to verify identities properly.
This operating environment makes retail banking a high-pressure, process-bound industry. Banks need staff who can navigate rigid compliance rules while still meeting quarterly branch sales targets. It is an industry where the risk appetite is low, scrutiny is high, and operational discipline matters far more than creative thinking.
Where this role fits in the structure
The title Universal Advisor reflects the modern branch model. Historically, a bank branch separated functions completely: tellers handled cash, enquiries clerks printed stamped statements, and personal bankers sat in private offices selling loans and opening accounts. That structure was expensive and slow. Today, banks cross-train staff into hybrid positions that can handle both service issues and direct sales in real time.
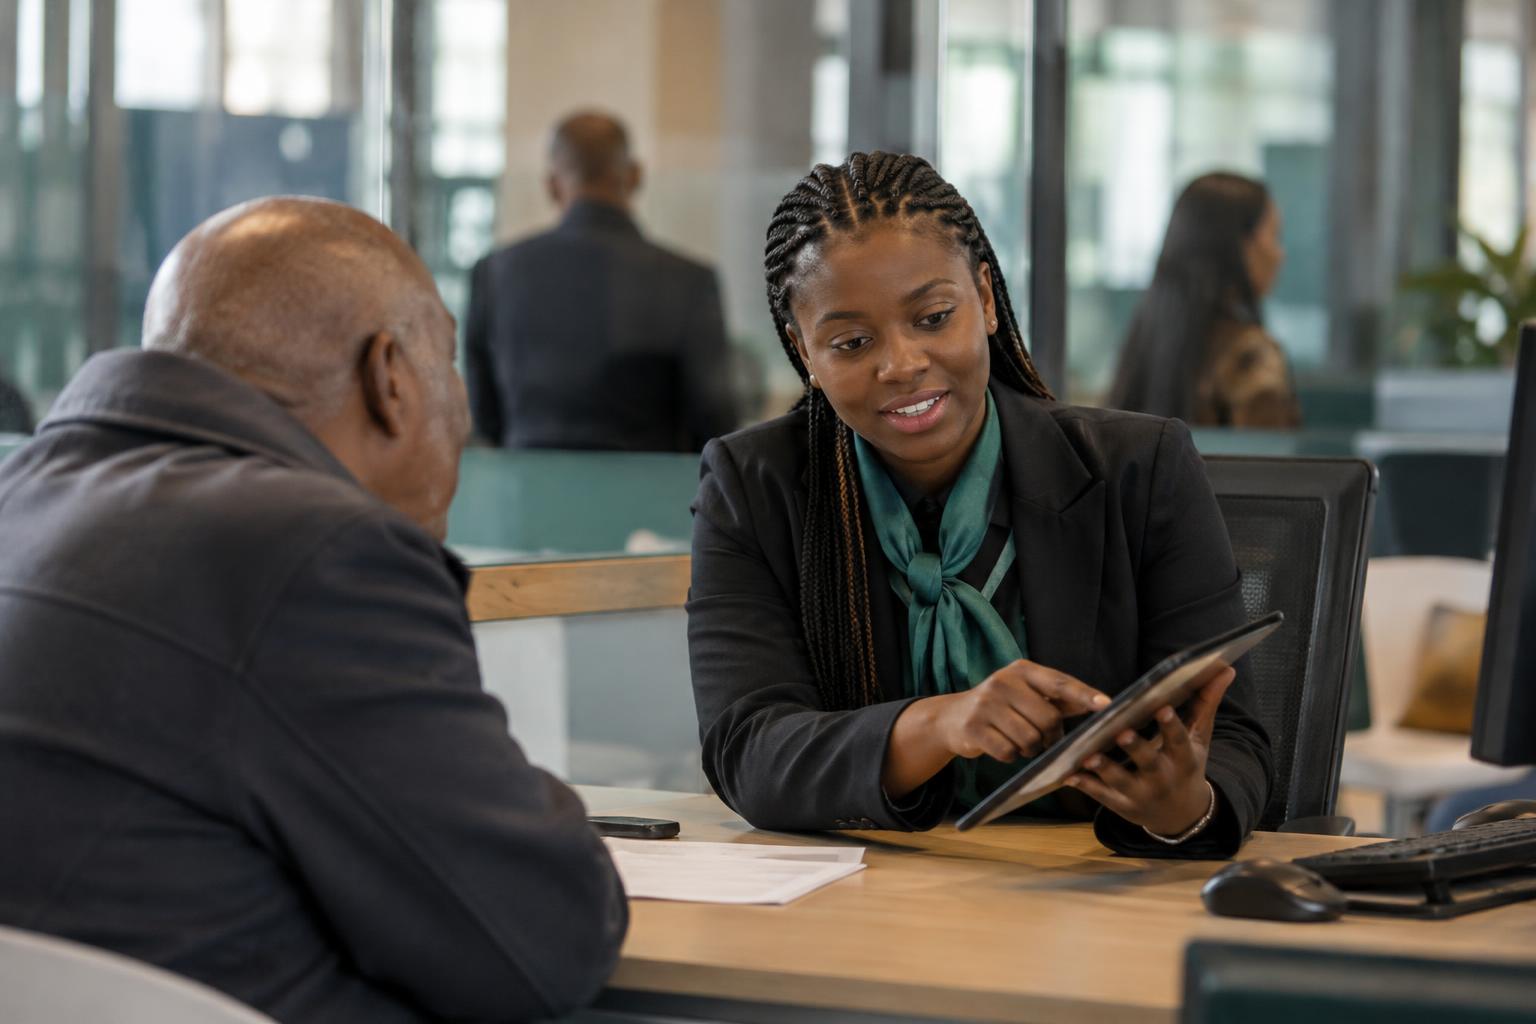
A Universal Advisor vacancy sits directly on the branch floor. You are the operational bridge between the queue and the bank's balance sheet. When a walk-in customer arrives, you assess their query, resolve immediate service blockers, and migration-coach them toward digital channels so they do not return to the branch for simple transactions. While doing that, you identify cross-selling opportunities: an upgraded cheque account, an overdraft facility, personal loans, funeral cover, or short-term insurance.
The day-to-day rhythm of this work in an urban centre like Johannesburg involves dealing with high volumes of people under time pressure. Customers often arrive frustrated because something went wrong on their app or an automated deduction took place. Your job is to calm the client, fix the administrative block, document every interaction according to Treating Customers Fairly (TCF) guidelines, and convert that interaction into a retention or sales win where appropriate. You report directly to a Branch Manager or Team Leader who monitors daily tallies: digital migrations completed, product uptake, audit scores, and customer turnaround times.
What the sector rewards in candidates
Getting hired into a junior banking position requires understanding what branch managers actually worry about. A branch manager fears audit findings, customer complaints escalated to the ombud, and missed quarterly sales volumes. Candidates who demonstrate they can balance compliance with interpersonal stamina get preference.
Key traits that banking recruiters look for include:
- Regulatory comprehension: Candidates who know what FAIS, FICA, and TCF mean in practice, rather than just repeating acronyms, immediately stand out. Demonstrating an understanding of regulatory compliance shows you will not create legal liabilities for the branch.
- Emotional resilience: Working face-to-face with the public about money is taxing. People become aggressive when their accounts are frozen or loans are declined. Staff who maintain steady composure and clear communication thrive, while those who take customer frustration personally burn out fast.
- Sales comfort without recklessness: Banks do not want rogue salespeople who cut corners to meet targets. They look for disciplined professionals who spot legitimate customer needs, explain fee structures accurately, and close the product uptake cleanly.
- Administrative precision: If you forget to upload a certified proof of residence or fail to log a referral accurately on the system, the branch fails its internal audit. Attention to detail on paperwork is non-negotiable.
For anyone looking to apply for banking vacancies in 2026, holding an NQF 5 qualification recognised by the Financial Sector Conduct Authority (FSCA) provides a substantial advantage over candidates who hold only a Matric. While a standard Grade 12 certificate gets your foot in the screening pool, recognised regulatory exam credits or banking certificates show the recruiter that you can be placed on a commercial register with minimal initial training delay.
Realistic progression from here
Starting as a Universal Advisor provides one of the best ground-level foundations in South African corporate finance. You learn the core mechanics of personal banking: credit vetting, account onboarding, risk profiling, and client relationship management. You also learn how to hit structured targets under constant scrutiny.
The progression path typically branches into three distinct directions after two to four years of consistent performance:
First is specialised branch banking. Strong performers often move upward into Private Banking or Premier Banking, managing a dedicated portfolio of higher-net-worth individuals. From there, commercial and business banking relationship management becomes accessible, where you manage portfolios of small and medium enterprises. These roles offer significantly higher earning potential, better working hours, and less transactional foot-traffic pressure.
Second is branch leadership. If your strength lies in managing workflows, audits, and coaching junior colleagues, the next logical steps are Assistant Branch Manager, Branch Operations Manager, and ultimately Branch Manager.
Third is lateral movement into head office corporate functions. Many professionals working in retail risk assessment, product design, fraud investigations, and compliance at head offices in Sandton or central Johannesburg began their careers inside a branch. Having practical knowledge of how frontline banking systems function and how real consumers behave makes you an asset to risk and product teams. The ceiling is determined almost entirely by your willingness to complete relevant post-Matric financial qualifications while working.
Apply for this job
Universal Advisor at FirstRand (FNB) · Johannesburg
View the listing and applyRead next
- Absa is hiring entry-level lead generators in Johannesburg and across GautengWhat retail bank lead generation actually involves, how the recruitment process works, and how to set up your CV to pass screening.
- Clover hiring 2 Laboratory Assistants in Queensburgh for 2026: Matric requiredHere is how hiring for entry-level lab assistant roles works at major dairy plants in South Africa, including how to format your CV and prepare your documents.
- Motus Corporation Year 1 Motor Apprentice in Parktown Requires MatricMotus Corporation is hiring a Year 1 Motor Apprentice for its workshop in Parktown, Gauteng. Applicants need a Matric certificate for this permanent opportunity closing on 4 September 2026.
- Umalusi Receptionist Vacancy in Pretoria Requires Matric for Permanent RoleUmalusi is accepting applications for a permanent Receptionist position at its offices in Pretoria, Gauteng. Candidates with a Matric qualification have until 2 September 2026 to apply.